Flexible Options for Your Next Home.
Purchase a home, explore a property with multiple units, or finance renovations with conventional loan options built around your goals. Enjoy competitive rates, fast closings, and personalized service from application to closing.
*Subject to credit, underwriting, property, income, and program requirements.
Flexible Financing. Built Around Your Financial Picture.
Conventional loans offer down payment options as low as 3% to 5% for qualified buyers. Many lenders look for 620+ FICO, but Fannie Mae automated underwriting has no minimum credit score. Lower scores in the 400s or 500s may be possible with a larger down payment and sufficient reserves, subject to lender requirements.
Apply Now3% – 5% Down
Low down payment options for qualified buyers.
620+ FICO
Many lenders look for 620+ FICO, with options for lower scores in some cases.
Stronger Credit May Mean Lower PMI
A higher credit score may help you qualify for a lower mortgage insurance premium (PMI).
HomeReady and Home Possible
Eligible buyers may qualify for as little as 3% down with Fannie Mae HomeReady or Freddie Mac Home Possible. Reduced mortgage insurance coverage requirements may lower your PMI. Many participating lenders look for 620+ FICO. Income limits, homebuyer education, and program requirements apply.
Live in One. Rent the Others.
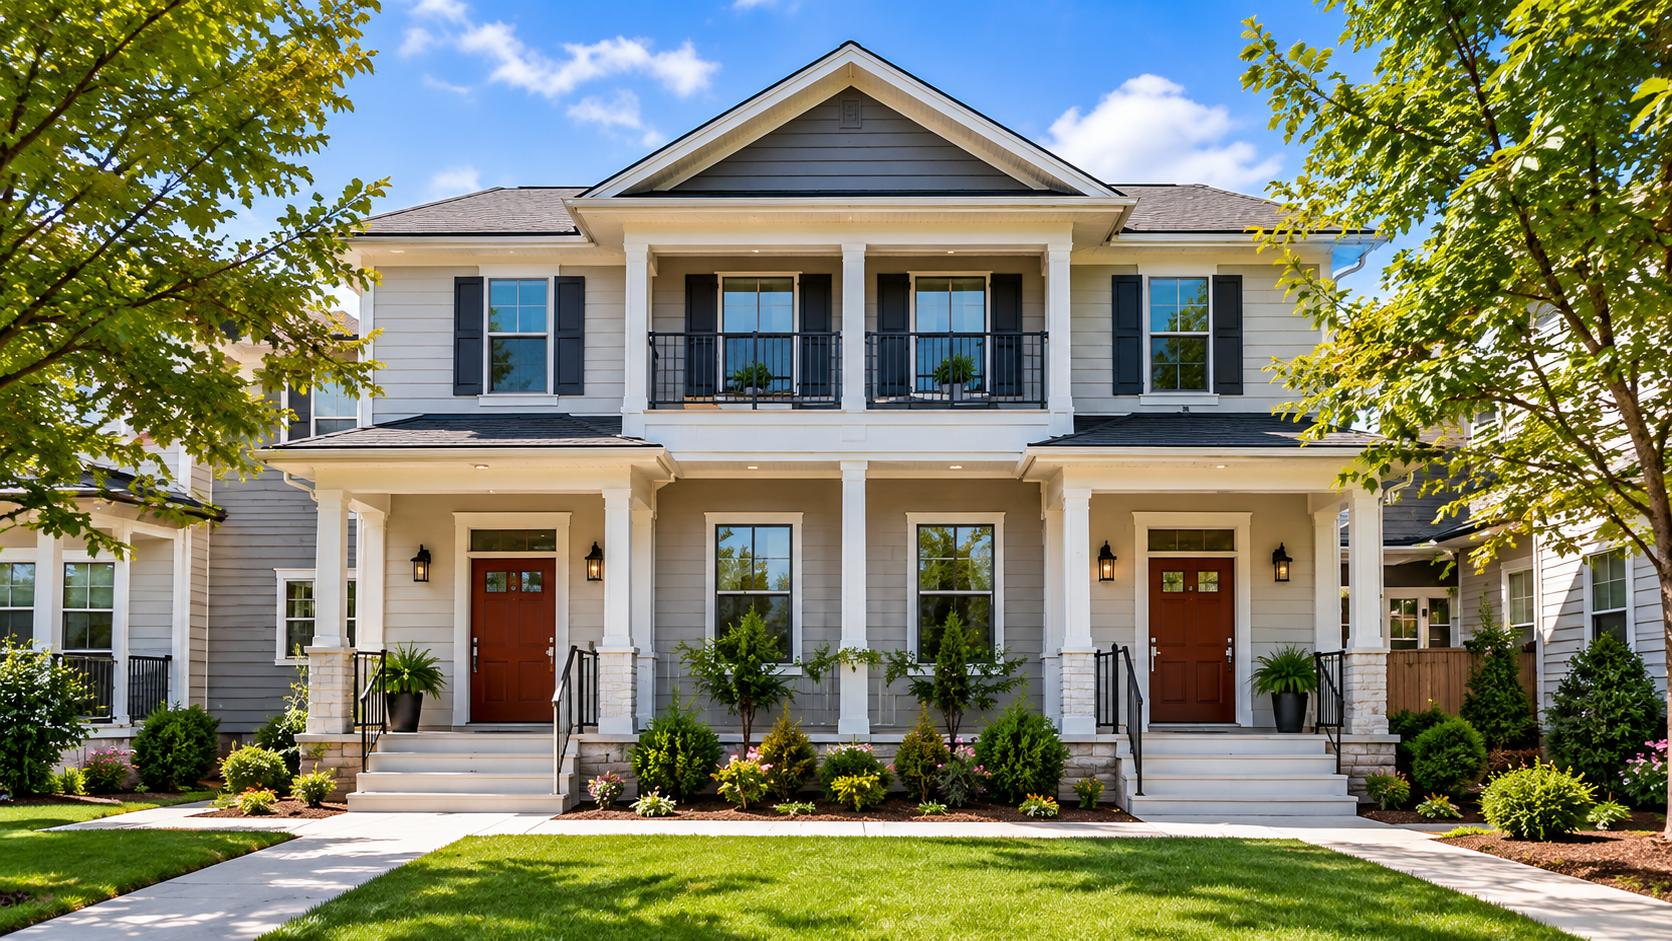
Eligible buyers can purchase a duplex, triplex, or fourplex with as little as 5% down. You must occupy one unit as your primary residence, generally within 60 days, and intend to remain for at least 12 months. Qualifying rental income from the other units may help you qualify. Additional reserves and underwriting requirements apply.
Primary Residence
Owner occupancy generally within 60 days and for at least 12 months.
Use Rental Income
Qualifying rental income may help you qualify.
Additional Requirements
Larger reserves and underwriting requirements may apply.
Turn a Home Into Your Dream Home
Fannie Mae HomeStyle Renovation allows you to combine your mortgage and qualifying renovation costs into one loan. Options start at 620+ FICO, subject to lender requirements. A higher credit score may help you qualify for better pricing. Use the funds to update kitchens, bathrooms, make layout improvements, and more.
Eligible Property Types
Conventional financing can be used for a variety of property types, all subject to applicable program and lender requirements.
Single Family Homes
Modular Homes
Eligible Manufactured Homes
Townhomes
Multifamily Properties (Up to 4 Units)
Financing Up to the Applicable Conforming Limit
Loan amounts are available up to the applicable conforming loan limits for your location and number of units. Higher loan limits may be available in designated high-cost areas.
Ready to Explore Your Conventional Options?
Get clear answers, personalized guidance, and a financing strategy designed around your goals.