Your Credit Score Does Not Have to End Your Homeownership Journey.
You earned your VA home loan benefit. Let's explore how to put it to work.
VA does not set a minimum FICO score. Lender requirements vary, but we offer options that look beyond the score to evaluate your complete financial picture.
Our recent VA closings include buyers with FICO scores of 534, 537, 550, 560, 571, 585, and 601.
No Minimum FICO
Options for a wide range of credit profiles.
0% Down Options
Purchase with no down payment.
2 – 4 Unit Options
Buy a duplex, triplex or fourplex.
No Monthly Mortgage Insurance
Keep more of your money.
Subject to credit, income, entitlement, property, lender, and program requirements.
No Minimum FICO. Personalized Guidance.
A lower credit score does not automatically disqualify you from a VA loan. We review your credit history, income, debts, residual income, and available funds to identify a realistic path forward.
Manual underwriting is available for eligible borrowers who meet applicable requirements.
Apply Now →Credit History
We look at your full credit history, not just your credit score.
Income & Debts
We review your income, existing debts, and overall financial picture.
Residual Income
Your remaining income after expenses is an important factor.
Manual Underwriting
Available for eligible borrowers who meet program requirements.
Purchase With 0% Down
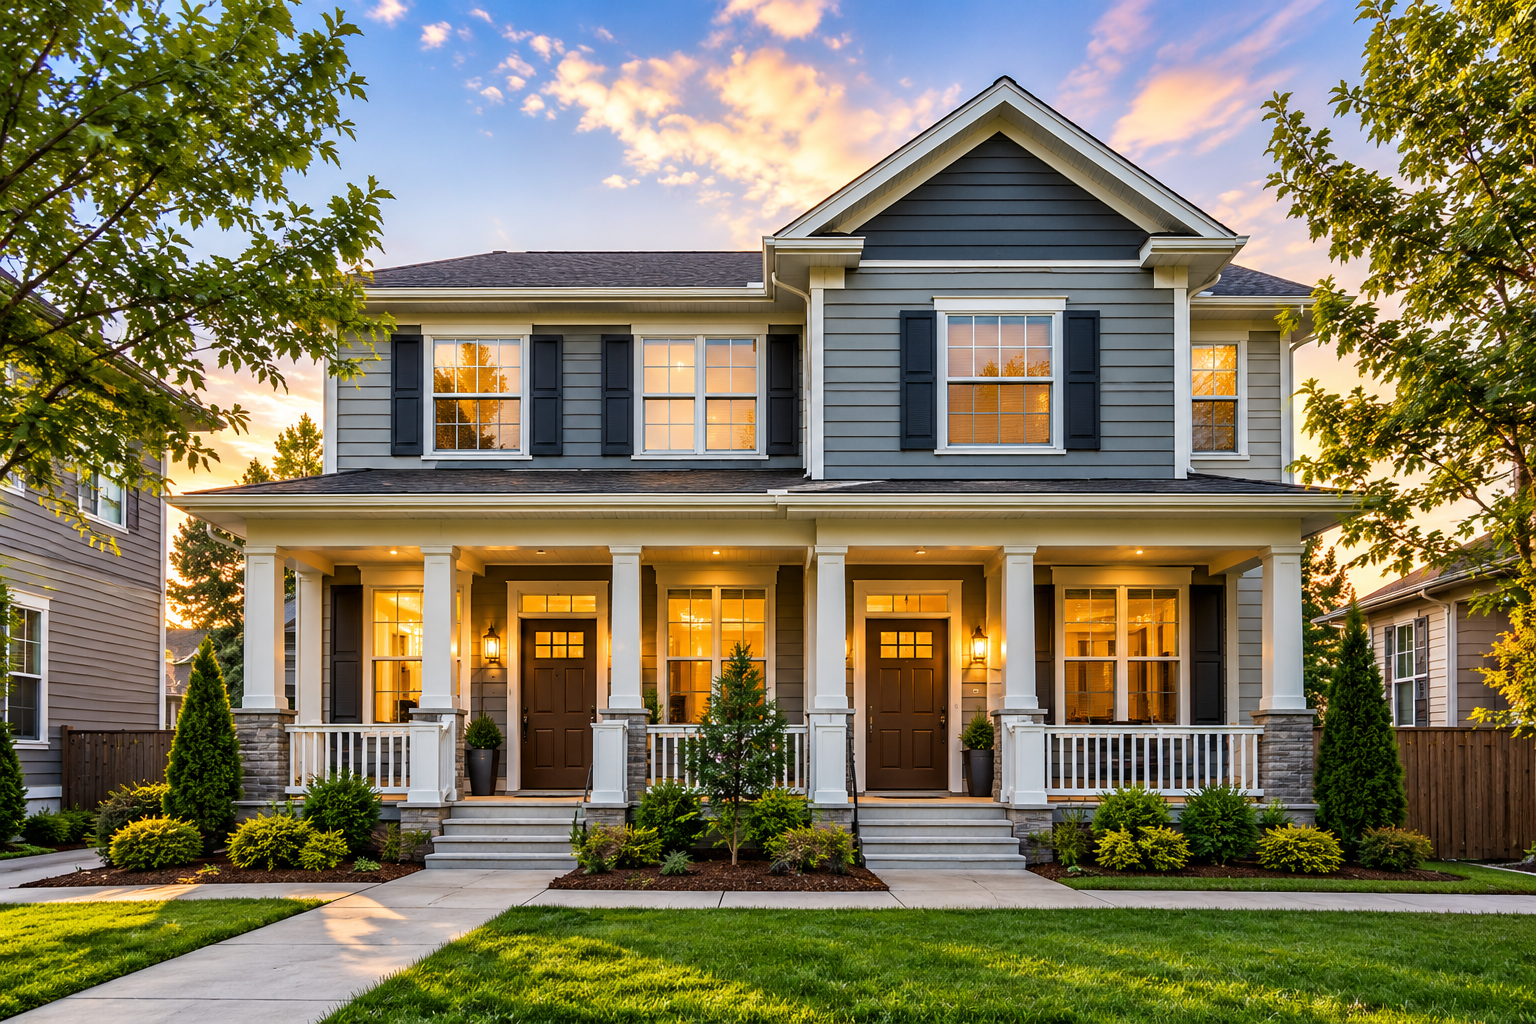
Eligible buyers may purchase a primary residence with no down payment and no monthly mortgage insurance, subject to sufficient entitlement, appraised value, and lender approval.
Primary Residence
Purchase your primary residence with 0% down.
No Monthly Mortgage Insurance
Lower your monthly housing costs.
Preserve Your Savings
Keep more savings available for moving, emergencies, and life after closing.
Buy It. Modernize It. Make It Yours.
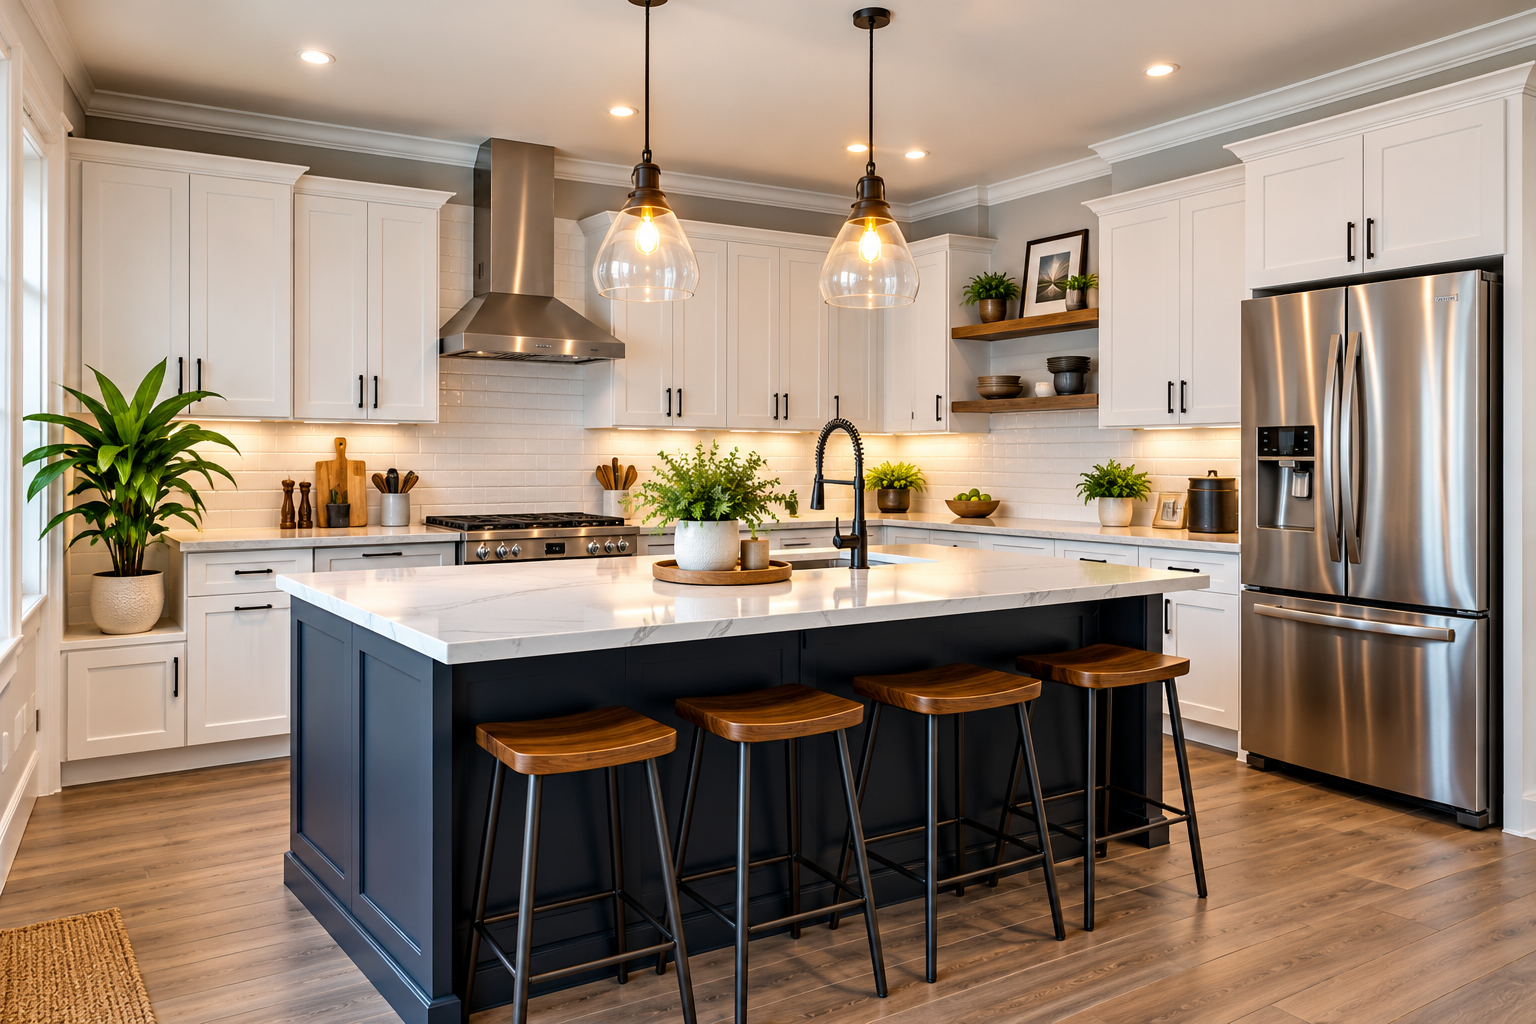
Buy a home and finance approved improvements in one mortgage. Renovation options start at 580+ FICO, with manual underwriting available for eligible borrowers.
Modernize an outdated home with approved updates that fit your needs and style. Renovation scope, contractor approval, and lender requirements apply.
Apply Now →Benefits for Veterans With 100% Disability
We help veterans with 100% service connected disability ratings understand their financing options and applicable benefits.
Funding Fee Exemption
Veterans receiving qualifying VA disability compensation are generally exempt from the VA funding fee.
Disability Income
Documented VA disability income may be used to qualify.
Tax-Exempt Income
Eligible tax-exempt income may receive favorable qualifying treatment.
Property Tax Benefits
State or local property tax exemptions may be available.
You do not need a 100% disability rating to qualify for a VA funding fee exemption. Property tax benefits vary by location and require separate verification.
Explore Your Refinance Options
Looking to lower your interest rate, access equity, or move from an adjustable rate to a fixed rate? We have options to help.
VA IRRRL
A streamlined refinance for your existing VA loan. May help you lower your interest rate or move from an adjustable rate to a fixed rate.
VA Cash Out Refinance Up to 100% LTV
Eligible homeowners may refinance up to 100% of the home's appraised value. Use equity for home improvements, debt consolidation, major expenses, or other goals.
Seller Credits Can Reduce Your Upfront Costs
VA places no percentage cap on seller credits toward allowable closing costs. Separately, seller concessions may cover eligible debt payoff and other permitted expenses, up to 4%.
Eligible Property Types
VA financing can be used for a variety of property types, all subject to applicable VA and lender requirements.
Single Family Homes
Townhomes
Condos in VA Approved Projects
Eligible Manufactured Homes
Modular Homes
Properties with 2 to 4 Units
A Clear Strategy. Personalized Service.
Whether you have strong credit, a score in the 500s, disability income,
or a file that needs manual underwriting, you deserve clear answers
and a thoughtful review.
We help you understand your options, prepare your documentation,
and move forward with a plan.